
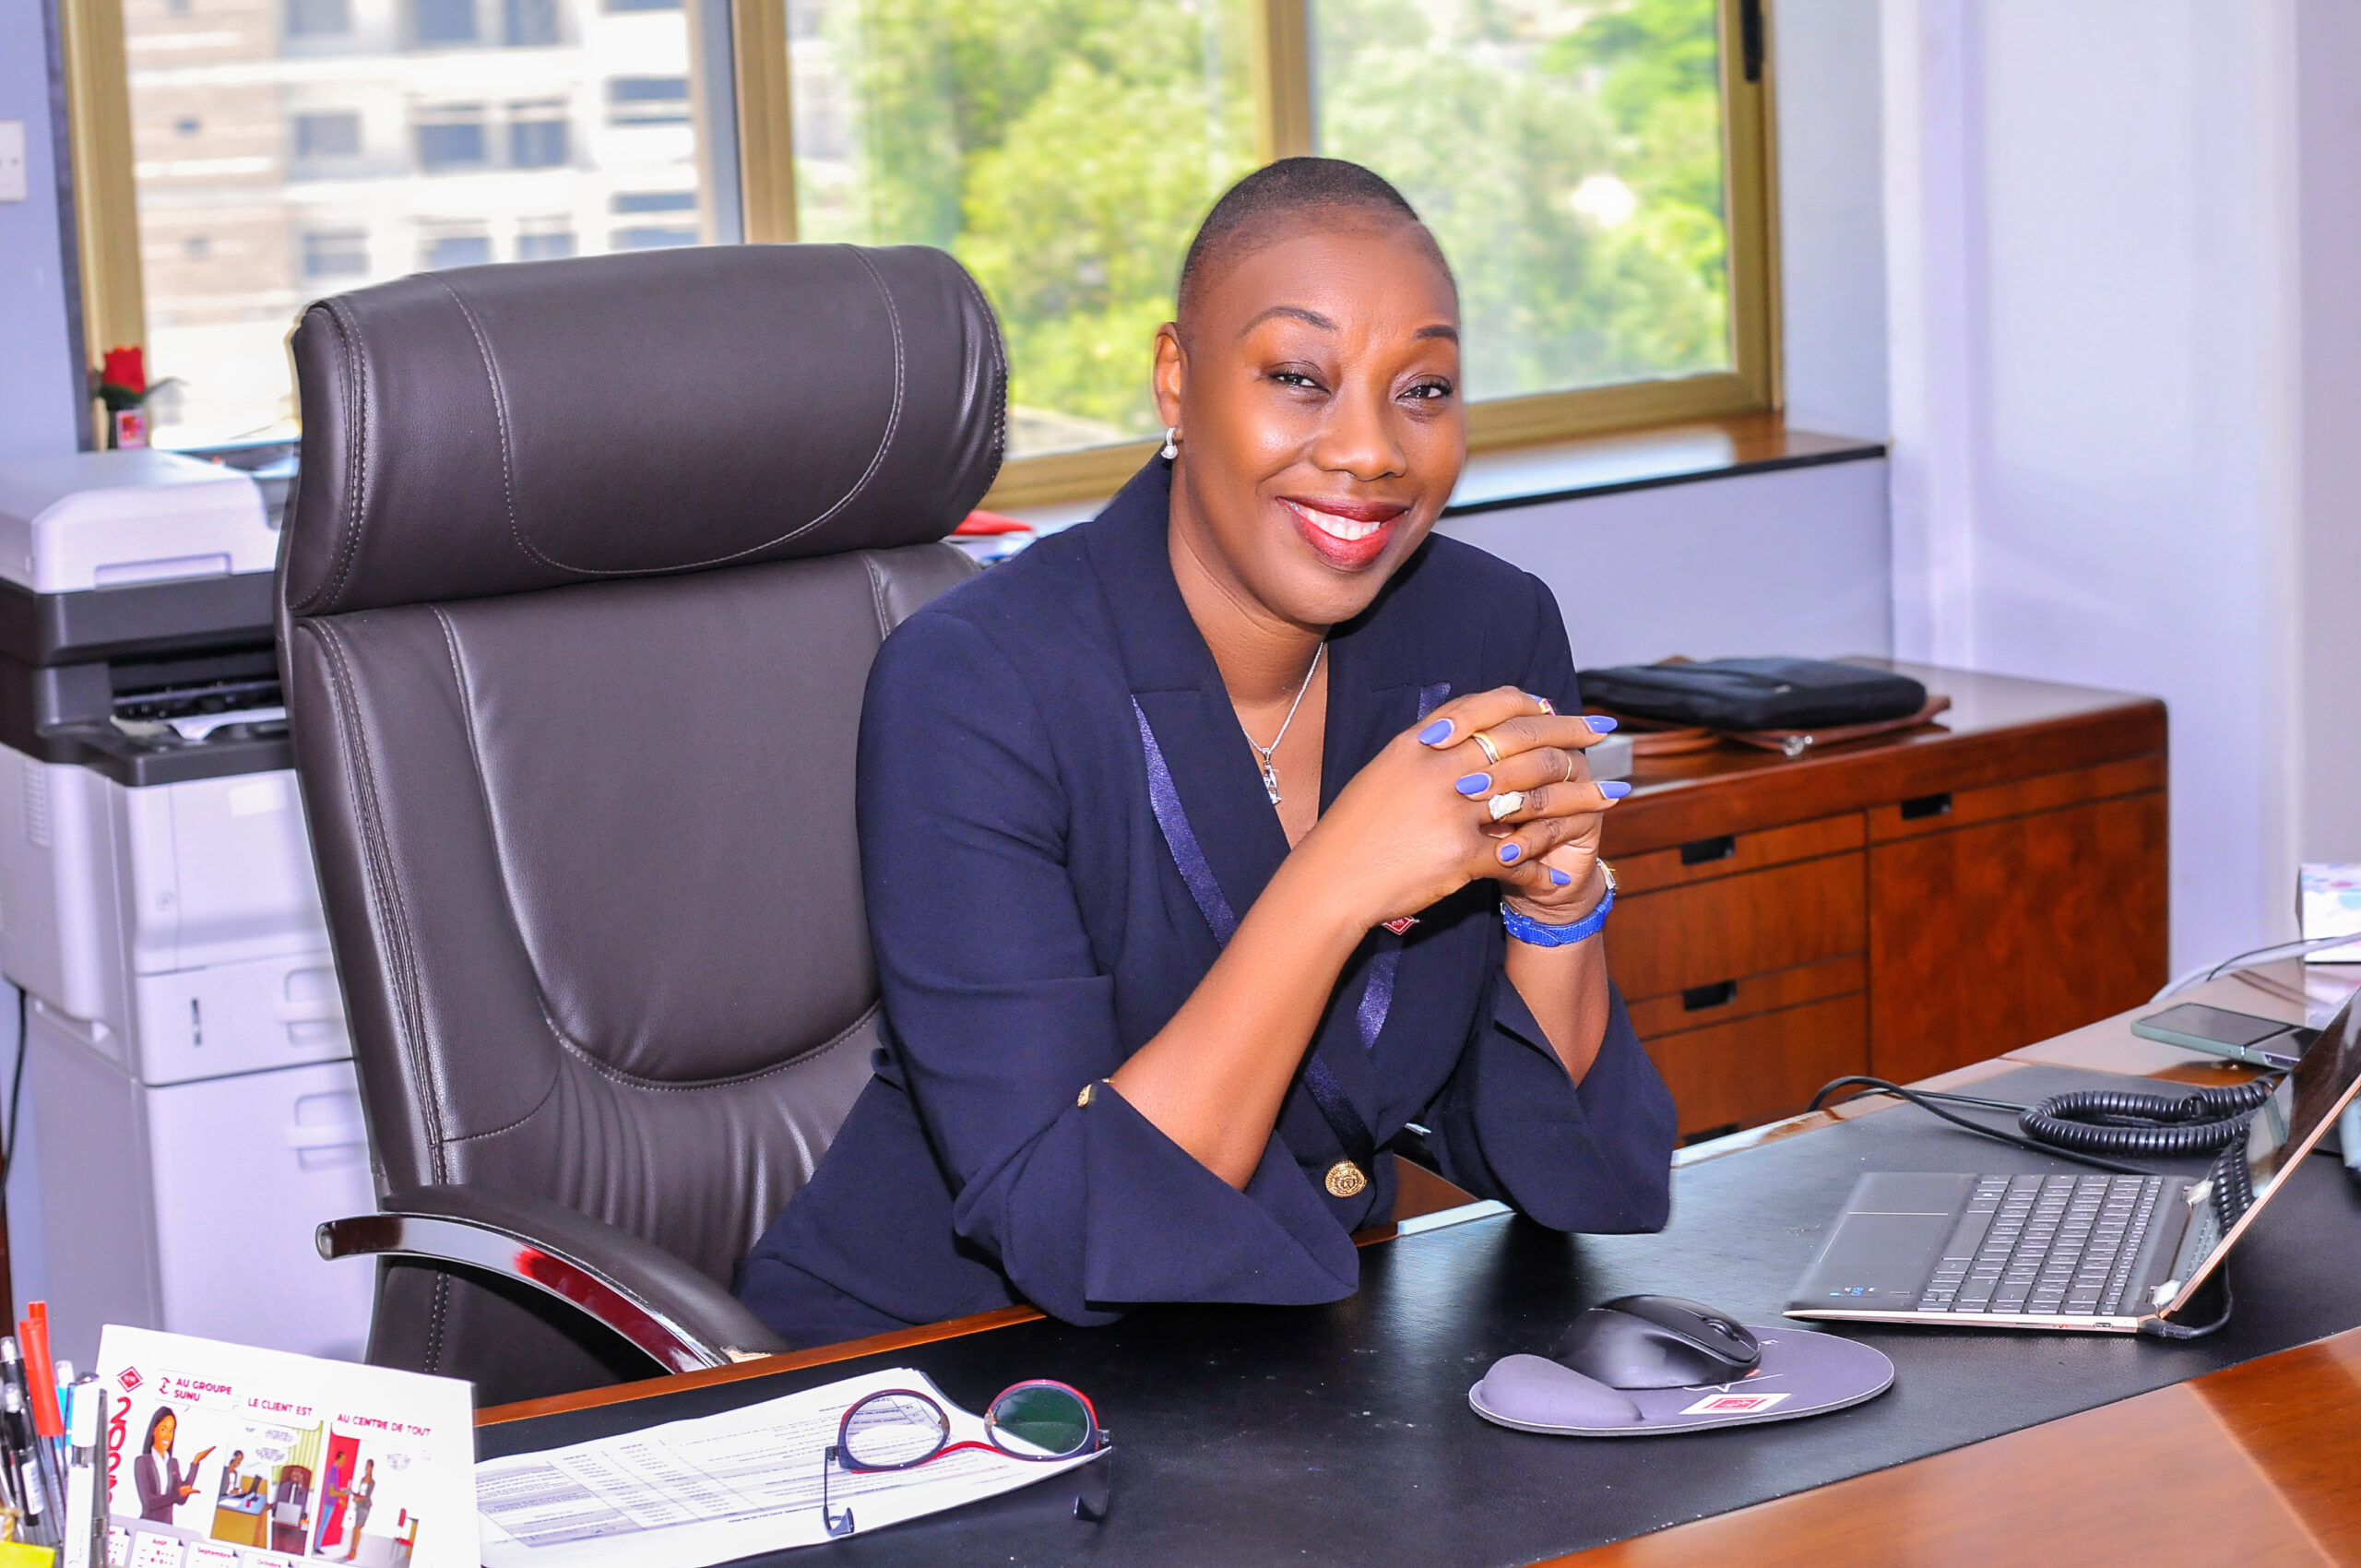
At the helm of SUNU Investment Holding since 2024, Myriam Agbanglanon Adotevi is steering the consolidation and development of the banking division of the SUNU Group. With two establishments in Senegal and Togo, representing a total balance sheet of approximately 1,000 billion FCFA by the end of 2025, the group aims to accelerate its digital transformation, strengthen its financing of SMEs, and leverage synergies between banking and insurance. The recent entry of the International Finance Corporation (IFC) into the capital of the holding marks a new phase in this strategy. Between organic growth, prudent discipline, and targeted acquisitions, the director of SUNU Investment Holding reveals to Financial Afrik her ambitions for 2030, with a particular interest in the Ivorian market.
Since taking office at SUNU Investment Holding, what are the major strategic directions you have implemented for the banking holding of the SUNU Group?
When I took over the leadership of SUNU Investment Holding in 2024, our priority was clear: consolidate before accelerating. We worked simultaneously on three axes, with the common thread being the desire to ensure a quality of service that meets our clients’ expectations.
The first is integration. With SUNU Bank Senegal, formerly BICIS, we successfully completed the rebranding, the full migration of the information system, and the integration of the bank into the SUNU Group in 2025. This demanding project equipped the bank with modern tools and a more agile organization, allowing it to provide its clients with a better experience.
The second is transformation. At SUNU Bank Togo, we have initiated a deep transformation program: processes, organization, and tools, with the goal of better supporting the teams and providing clients with faster services and modernized digital channels.
The third is solidity. We have strengthened governance, risk management, and the security of our systems, including obtaining PCI DSS certification for both of our banks.
What position do you aim to occupy in the West African banking landscape by 2030?
Our ambition is to be a benchmark banking player, recognized for its solidity, its proximity to clients, and its ability to finance the real economy.
We have an asset: we belong to a pan-African group of insurance and banking, a leader in life insurance in the CIMA zone and present in 17 countries. This combination allows us to offer our clients a comprehensive response to their needs, and that is what will distinguish us.
By 2030, we want stronger banks in their markets, an increased role in financing SMEs, particularly those led by women, and a presence that will expand in line with genuinely value-creating opportunities.
How are the main financial indicators of your banking holdings evolving, particularly total balance sheet, net banking income, deposits, loans, and profitability?
By the end of 2025, our two banks will represent a total balance sheet of approximately 1,000 billion FCFA, an increase of 11%, with 572 billion in customer loans (+10%) and 719 billion in deposits (+7%). Net banking income will reach 55.3 billion FCFA, an increase of 2.4%.
2025 was a year of migration for SUNU Bank Senegal, thus a year of consolidation rather than conquest. However, profitability has significantly improved. The net income of SUNU Bank Senegal reached 15.3 billion FCFA, an increase of 27%, with a return on equity of 19%. Our efficiency has also improved, with the operating ratio reduced from 62.3% to 58.8%, and the cost of risk decreased by about 25%.
At SUNU Bank Togo, net banking income is up by 11%. This is an encouraging signal for a bank undergoing transformation, with indicators expected to improve in 2026.
What are your main value creation levers today?
The first is commercial growth and the strategy deployed particularly towards SMEs. These are segments with potential, where our banks can play a driving role while continuing to serve individual clients and large enterprises.
The second is the complementarity with insurance. Belonging to a group that combines banking and insurance allows us to offer our clients comprehensive solutions and strengthen their loyalty.
The third is operational efficiency. We are doing everything possible to simplify and automate our processes to improve service and offer more digital solutions to our various client segments.
The fourth is risk management. Growth has value only if it is sound. The decrease in our cost of risk shows that this discipline is paying off.
The SUNU Group has built part of its development on strategic acquisitions. Are you considering new external growth operations in the African banking sector?
Which markets and which types of institutions particularly attract your attention?
External growth is part of the Group’s DNA, and our banking ambition remains intact. However, in recent years, we have made a methodological choice: first succeed in integrating our two banks and consolidate their growth.
We are in a position to explore new opportunities; we do this with discipline: an operation makes sense only if it creates value for our clients and shareholders and if we are able to integrate it under good conditions.
Our natural priority is the markets where the Group is already present. This is where the complementarity between banking and insurance creates the most value and where we know clients and ecosystems best.
Côte d’Ivoire, where our holding is based and where the Group conducts nearly 30% of its activities, is naturally a market that attracts our attention, as well as other countries where the Group is already present and where banking can provide real added value.
The convergence between banking and insurance represents a potential competitive advantage for SUNU. How do you plan to transform this complementarity into a true integrated bancassurance model?
This is a strong conviction of the Group, and we have begun to lay the foundations. Bancassurance requires banks integrated into the Group and equipped with modern tools. This is what we are building with SUNU DigiTech, the Group’s subsidiary dedicated to the information systems of all its activities.
In concrete terms, the idea is simple: to offer our clients a single point of contact for all their needs, from savings to credit, from protection to prevention.
We are developing offers that combine credit, protection, and prevention to support our clients at every stage.
And in markets where insurance is still underdeveloped, banking provides natural access to banked clients who are not yet insured.
In light of the rise of fintechs, mobile money, and digital banks, how is your model evolving?
We do not see these players as competitors. They have transformed client expectations, who now want simple, fast, and accessible services at any time. It is up to us to also meet these expectations.
We are investing heavily in this direction. The MySUNU Bank app allows our clients to manage their accounts 24/7 and even subscribe or track their insurance policies with SUNU Assurances. In Togo, we were pioneers with WhatsApp Banking. Our information systems give us the agility needed to launch new services faster, and the PCI DSS certification of our two banks ensures a high level of security.
We are also analyzing partnership opportunities. Mobile money and fintechs bring proximity and speed; a bank brings trust, solidity, and the capacity to finance. These two worlds are complementary.
In an environment marked by tightening regulatory requirements, pressure on margins, and significant financing needs of African economies, how do you reconcile growth, financial solidity, and risk-taking?
This is the challenge of banking today. For us, solidity and growth do not oppose each other: the former is the condition for the latter.
We act on three levers. First, our equity: we are strengthening our financial base to anticipate the increase in regulatory requirements. Next, risk management, which we are enhancing at all levels. Finally, efficiency: modernized processes allow us to better withstand pressure on margins.
It is this discipline that enables us to take measured risks where needs are greatest, particularly with SMEs.
Is SUNU Investment Holding considering new capital openings or strategic partnerships to finance its ambitions?
We have just taken an important step with the entry of the IFC into our capital. This is a strong mark of confidence in our trajectory.
Beyond capital, the IFC brings us its expertise in risk management, SME financing, and governance, and will join our board of directors. This partnership gives us the means to strengthen our banks and finance more SMEs, particularly those led by women.
Our ambitions are also part of the CSR approach we are undertaking to fully integrate environmental and social issues into our business. For us, a responsible, transparent, and inclusive bank is also a stronger bank in the long term.
Box
BIOGRAPHY OF Mrs. Myriam AGBANGLANON ADOTEVI
Myriam Agbanglanon Adotevi, a 57-year-old Beninese, is a graduate of a business school and holds the CESA HEC General Management certificate; she began her banking career at Ecobank Benin in 1997, where for 15 years she held various commercial positions (Institutional Banking Account Manager, Branch Manager, Corporate Banking Director, then Retail Banking Director, Executive Administrator).
In 2012, she joined the BGFI group in Gabon, and in 2013 she took over the management of the BGFIBank Benin subsidiary, which she led for 5 years.
In 2018, she joined the SUNU Group to develop its banking division through the acquisition of Banque Populaire BPEC, formerly Caisse d’Epargne du Togo, which became SUNU Bank Togo, which she managed for 5 years.
To date, as the General Director of SUNU Investment Holding, she is responsible for the development of the banking division of the SUNU Group, currently consisting of SUNU Bank Togo and SUNU Bank Senegal (formerly BICIS).
She has served on the boards of companies in Togo from 2019 to 2023 (SGI Togo, Togo Rail, Opti Asset Management) and is currently a member of the Board of Directors of Kajas Microfinances Senegal/Witti Finances (Chair of the Audit Committee), SUNU Bank Senegal (member of the Credit Committee), and JULAYA Benin.